Invoice Processing Outsourcing Blends Human Review With the Automation Finance Teams Now Expect

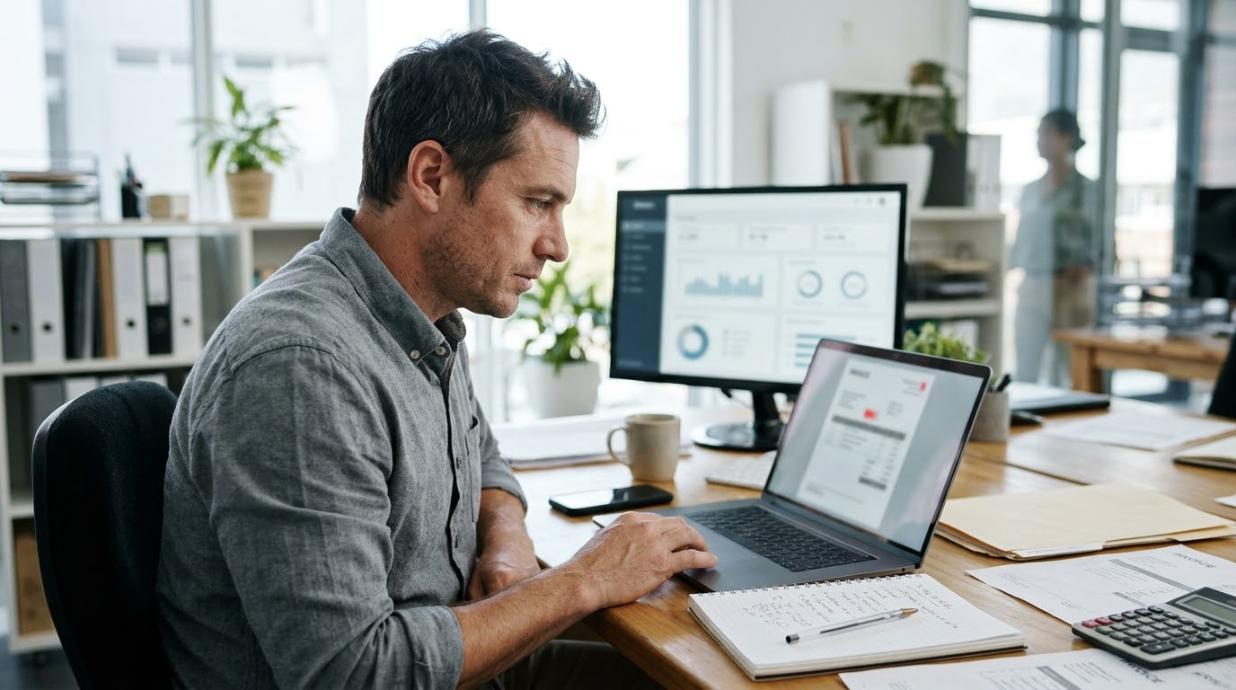
A specialist reviewing an exception through invoice processing outsourcing with automated tools supporting the work.

Invoices used to arrive as paper, get typed into a system, and wait in a pile for approval. Today they arrive as PDFs, emails, and electronic files, and software can read many of them in seconds.

Yet automation alone does not finish the job. Odd formats, missing details, and unusual charges still need a human eye. Invoice processing outsourcing brings both together, combining modern tools with trained people who handle the exceptions and keep the numbers trustworthy.

From Paper to Data

The first step is turning an invoice into usable data. Optical character recognition and AI-based document tools read the supplier name, invoice number, dates, line items, taxes, and totals.

These tools learn patterns over time, so accuracy tends to improve. Good capture reduces typing, and it gives finance teams cleaner records from the start.

Where Humans Still Matter

Not every invoice is clean. Handwritten notes, scanned images, new suppliers, and unusual layouts can confuse software.

Trained staff review flagged items, correct fields, and decide how to code unclear charges. This human-in-the-loop approach keeps accuracy high without slowing the entire process.

Matching and Approvals

After capture, invoices are matched to purchase orders and goods receipts, a step often called three-way matching. When details agree, the invoice can move forward. When they do not, someone investigates.

Workflow tools route invoices to the right approvers, remind them of deadlines, and keep a record of every decision.

Integration With Accounting Systems

Data is only useful if it reaches the books. Providers often work inside the client’s ERP or accounting platform, such as QuickBooks, Xero, or NetSuite, or connect through APIs.

Integration avoids re-entry and keeps vendor, tax, and account information consistent. Clear field mapping at the start prevents confusion later.

E-Invoicing and Standard Formats

More governments and businesses use structured electronic invoices that arrive as data rather than images. These formats reduce errors and speed processing.

Providers that understand them can help clients adopt standards and handle both structured and unstructured invoices during the transition. Flexibility is valuable, since suppliers move at different speeds.

Cost and Scalability

Processing costs depend on volume and complexity. Outsourcing turns fixed staffing into flexible fees, and providers can scale up during busy periods.

Technology investments are shared across many clients, which can lower costs for each. Buyers should still compare total costs, including setup, oversight, and exception handling.

Controls and Fraud Prevention

Invoices are a common target for fraud, from duplicates to fake suppliers. Controls such as duplicate detection, vendor verification, and approval limits reduce risk.

Providers should explain their checks and respect the client’s authority over payment release. Written procedures and audit trails support accountability.

Security and Data Protection

Invoices contain bank details, tax numbers, and commercial terms. Providers should use access controls, encryption, and monitored systems, and follow recognized standards such as ISO 27001.

Innovature states that it holds this certification and follows GDPR requirements. Clients should ask for evidence and understand where data is stored.

Measuring Performance

Useful measures include processing time, accuracy, the share of invoices handled without manual touch, and the time to resolve exceptions.

Reporting on these figures each month shows progress and highlights problems. A rising touchless rate, with stable accuracy, suggests that the process is improving.

The Direction of Fintech

Automation in finance keeps advancing. Coverage on how agentic AI is transforming financial technology platforms describes systems that can carry out multi-step workflows and monitor for fraud and compliance issues.

Outsourcing providers adopt such tools gradually, with human oversight, so clients can benefit while keeping control of important decisions.

Choosing a Provider

Look for a provider with experience in your industry, strong security, and clear reporting. Ask how its technology works, how exceptions are handled, and what happens when systems fail.

A pilot with a subset of suppliers shows how the team performs in practice.

Plan the Transition

A smooth start requires preparation. Clean up vendor records, document approval rules, and agree on formats and timelines.

Running old and new processes in parallel for a short time catches mismatches. Clear communication with suppliers about where to send invoices prevents confusion.

Tools and Judgment Together

The best results come from pairing tools with people. Software handles volume and speed, while skilled staff handle nuance and accountability.

Invoice processing outsourcing, done well, gives finance teams that balance without requiring them to build it all alone.
The New Financial Stack: What Happens When AI, Stablecoins and Tokenization Converge?

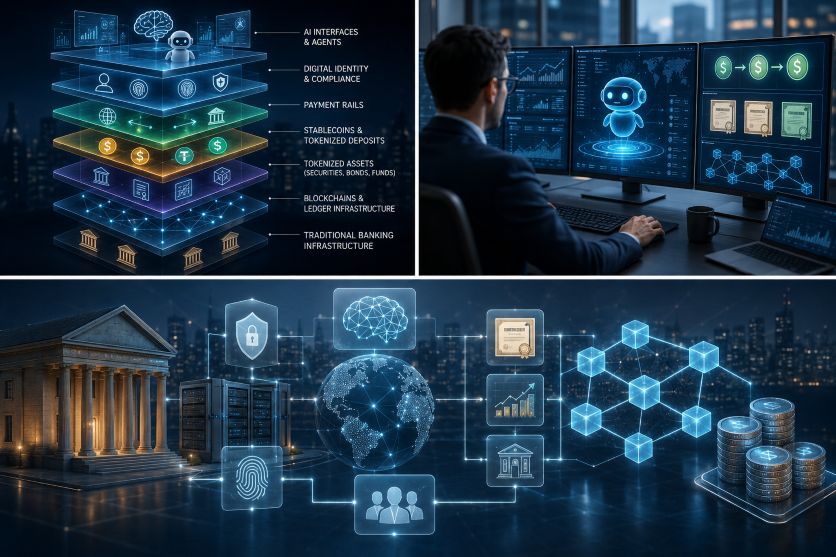
Futuristic Fintech Infrastructure Infographic

Financial technology is moving toward a new architecture. Artificial intelligence is automating analysis and financial operations, while stablecoins and tokenization are changing how money and assets can move across digital networks. The Financial Stability Board reported in June 2026 that financial institutions are already using AI to transform operations and services, while warning that rapid adoption can introduce or amplify financial risks.

Regulation is starting to adjust to that shift. On August 18, 2026, the U.S. Securities and Exchange Commission proposed Regulation Crypto Assets. The framework would create tailored offering rules for certain investment contracts involving crypto assets, including two registration exemptions and a conditional safe harbor. It signals that regulators are considering rules designed around digital assets rather than simply applying older structures unchanged.

What Does the New Financial Stack Look Like?

The emerging system can be understood as several connected layers. AI interfaces and software agents sit near the top, interpreting instructions and making decisions. Below them, digital identity and compliance systems determine who can transact. Updated guidance from the National Institute of Standards and Technology covers identity proofing, authentication and federation, highlighting the importance of reliable identity controls in digital systems.

Payment rails, stablecoins and tokenized deposits can then provide different ways to transfer value. Tokenized assets add securities, bonds or other financial claims that exist as programmable digital representations. Blockchains or similar ledgers provide transaction infrastructure, while banks, custodians and central banks can remain connected underneath.

The Bank for International Settlements argues that tokenization could improve cross-border payments and securities markets. Its proposed next-generation model combines tokenized central bank reserves, commercial bank money and government bonds. However, the BIS also warns that current stablecoins can suffer from fragmentation and other weaknesses that limit their ability to function as the foundation of the monetary system.

What Changes When Software Can Move Money?

The convergence becomes more significant when AI moves from giving advice to taking permitted actions. A company could eventually authorize an AI agent to monitor cash positions, calculate upcoming obligations and initiate approved transfers. Another agent might compare tokenized investments, execute transactions within defined limits and produce compliance records.

This could make treasury operations and financial markets more responsive. Stablecoins may provide programmable payment instruments, while tokenized securities could make assets easier for software systems to interact with. The International Monetary Fund notes that stablecoins may improve some payments, especially across borders, although their global reach also creates challenges involving capital flows, oversight and financial stability.

Why Human Control Still Matters

More automation also creates a larger security problem. An incorrect AI decision, compromised identity credential or flawed smart contract could trigger transactions faster than people can intervene. Financial institutions therefore need controls covering authorization, cybersecurity, model oversight, transaction limits and accountability. The Financial Stability Board has emphasized governance and safeguards throughout the AI lifecycle as financial firms increase adoption.

The future financial stack may therefore be highly automated without becoming fully autonomous. AI could decide what action to recommend, digital identity could establish permission, stablecoins could provide settlement and blockchains could record ownership. Yet banks, regulators and human operators may still define the boundaries. The central challenge is making programmable finance faster without allowing speed and autonomy to outrun security, accountability and trust.

The Rise of Embedded Finance and What It Means for Everyday Digital Services

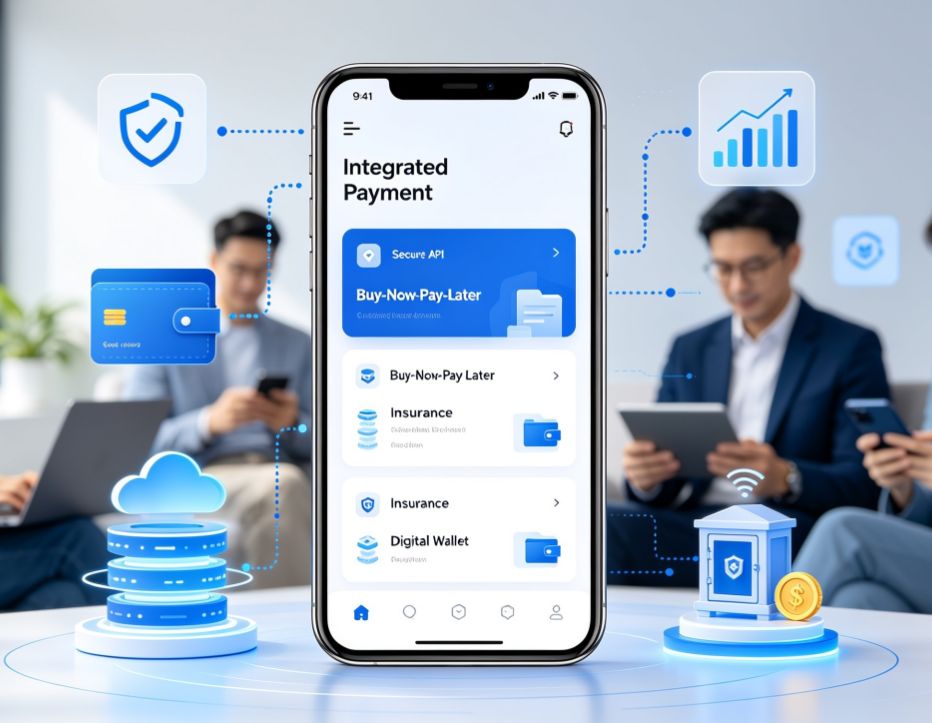
integrated payment

Digital payments, lending, insurance, and investment tools are increasingly being integrated into apps and online platforms that were never designed as financial institutions. Research from McKinsey & Company estimates that embedded financial services could generate hundreds of billions of dollars in annual revenue globally over the coming years, reflecting growing demand for seamless digital experiences.

One of the strongest drivers behind this shift is embedded finance, which allows customers to access financial products directly within familiar digital services. Instead of switching between separate applications, users can pay, finance purchases, insure products, or manage subscriptions without leaving an e-commerce site, ride-hailing app, or software platform. Reports from Accenture suggest that this integrated approach improves customer convenience while creating new revenue opportunities for businesses.

How Financial Services Became Part of Everyday Platforms

Digital platforms have evolved beyond their original purpose. Online retailers now offer installment payments, travel websites provide insurance during booking, and business software includes invoicing with integrated payment processing. Findings from Juniper Research indicate that consumers increasingly prefer these streamlined experiences because they reduce friction during transactions.

The technology behind this transformation relies heavily on application programming interfaces, cloud computing, and secure payment infrastructure. These technologies enable licensed financial institutions to connect their services with third-party platforms while maintaining compliance with industry standards.

Benefits for Businesses and Consumers

Companies gain several advantages by integrating financial capabilities into their existing products. Additional services encourage customer loyalty, increase transaction volumes, and create new income streams beyond traditional product sales. Research published by Deloitte notes that businesses offering integrated payment and financing options often strengthen customer engagement through more convenient purchasing experiences.

Consumers benefit from greater convenience and faster decision-making. Purchasing a product with financing, protecting it with insurance, or completing identity verification can happen during a single digital session. This reduces the need to complete repetitive forms across multiple providers while simplifying the overall customer journey.

Regulatory and Technical Considerations

Despite its advantages, integrating financial products into non-financial platforms introduces significant responsibilities. Financial services remain subject to regulations covering consumer protection, privacy, anti-money laundering requirements, and cybersecurity. Experts at the Bank for International Settlements emphasize that technology companies and financial institutions must clearly define responsibilities when delivering these services together.

Security remains another major priority. Data indicates from the World Economic Forum that growing digital connectivity increases exposure to cyber threats, making encryption, identity verification, and continuous monitoring essential components of financial technology ecosystems.

Future Outlook

The expansion of integrated financial services is expected to continue as consumers seek faster and more convenient digital experiences. Advances in artificial intelligence, open banking, and real-time payment networks will likely support even deeper connections between financial providers and digital platforms. Studies published by the Organisation for Economic Co-operation and Development (OECD) suggest that responsible innovation, combined with effective regulation, will play an important role in maintaining trust as these services become more widespread.

Financial capabilities are steadily becoming a standard feature of many digital products rather than a separate destination. Organizations that balance innovation with security, transparency, and regulatory compliance will be better positioned to meet changing consumer expectations while supporting a more connected digital economy.

How Agentic AI Is Transforming Financial Technology Platforms

fintech operations

Financial institutions are rapidly increasing their investments in artificial intelligence to improve operational efficiency, strengthen security, and meet growing regulatory demands. Reports from Deloitte and IBM indicate that financial firms are moving beyond traditional automation toward intelligent systems capable of making context-aware decisions. One of the most significant developments is agentic AI, which can plan, execute, and adapt multi-step tasks with limited human intervention.

AI-powered fintech platforms are beginning to integrate agentic AI into everyday operations, allowing software agents to coordinate workflows instead of simply responding to individual requests. Unlike conventional AI models that complete isolated tasks, agentic systems can analyze information, determine appropriate actions, monitor results, and adjust decisions as conditions change. This shift offers financial organizations greater efficiency while supporting more responsive customer and operational processes.

Automating Complex Financial Workflows

Traditional automation follows predefined rules, making it effective for repetitive activities but less capable of handling changing situations. Agentic AI expands these capabilities by connecting multiple business processes into coordinated workflows. A virtual agent can gather customer documentation, verify identities, request additional information when needed, initiate account approvals, and notify relevant teams without constant supervision.

Research from Accenture suggests that intelligent automation allows financial institutions to reduce processing times while improving consistency across departments. Experts note that combining workflow orchestration with machine learning enables employees to focus on strategic analysis instead of routine administrative work.

Strengthening Fraud Detection and Risk Monitoring

Financial fraud continues to evolve as cybercriminals adopt increasingly sophisticated techniques. Static detection systems often struggle to identify new attack patterns because they rely heavily on historical rules. Agentic AI introduces a more adaptive approach by continuously evaluating transactions, customer behavior, device activity, and network signals in real time.

Findings from Visa and studies published by the National Institute of Standards and Technology (NIST) show that combining AI with behavioral analytics improves the identification of unusual activity while reducing unnecessary alerts. Intelligent software agents can investigate suspicious events, prioritize cases according to risk levels, and recommend appropriate responses before human analysts complete final reviews.

Supporting Regulatory Compliance

Compliance requirements continue to expand across global financial markets. Monitoring regulatory changes, maintaining documentation, and preparing audit records require significant time and specialized expertise. Agentic AI can assist compliance teams by tracking policy updates, reviewing internal procedures, identifying potential gaps, and generating supporting documentation.

Reports from the Bank for International Settlements highlight the growing importance of advanced technologies that help financial organizations strengthen governance and improve regulatory reporting. Human oversight remains essential because compliance decisions often involve legal interpretation and organizational judgment.

Challenges to Enterprise Adoption

Despite its potential, implementing agentic AI presents practical challenges. Financial institutions must ensure high-quality data, strong cybersecurity controls, transparent decision-making processes, and effective model governance. Data indicates that explainability remains a priority because regulators and customers increasingly expect organizations to understand how AI-generated recommendations are produced.

Successful adoption also requires employee training, updated operational procedures, and careful integration with existing banking infrastructure. Organizations that introduce these systems gradually often achieve smoother deployment and better long-term performance.

Looking Ahead

Agentic AI represents the next stage of intelligent financial technology rather than a replacement for human expertise. As software agents become more capable of managing complex workflows, detecting fraud, and supporting compliance, financial professionals will increasingly oversee, validate, and refine automated decisions. Continued advances in governance, transparency, and responsible AI development will likely determine how widely these technologies are adopted across enterprise financial platforms in the years ahead.

How AI-Powered Financial Assistants Are Changing Consumer Banking and Wealth Management

banking and intelligent financial platforms

McKinsey & Company estimates that generative AI could add hundreds of billions of dollars in annual value to the banking sector, highlighting why financial institutions are rapidly investing in digital tools. Growing demand for personalized financial guidance has encouraged banks and fintech firms to develop intelligent financial platforms that help consumers manage money more efficiently.

Many people face challenges when budgeting, tracking spending, choosing investments, or identifying financial risks. Traditional advisory services can be expensive or difficult to access for everyday consumers. As a result, financial institutions have been searching for scalable ways to deliver personalized support while maintaining security and regulatory compliance.

How AI Is Addressing Consumer Financial Challenges

AI-powered assistants are emerging as a practical solution. Banks and financial technology companies now use machine learning to analyze transaction data, identify spending patterns, and generate customized recommendations. Research from Deloitte shows that AI is increasingly being integrated into customer service, fraud prevention, and financial planning tools across the financial sector.

Consumers can receive automated budgeting suggestions, savings goals, and alerts about unusual account activity. Investment platforms are also using AI-driven analytics to help users evaluate portfolio performance and understand market trends. Data from PwC indicates that financial firms view AI as a key driver of operational efficiency and improved customer experiences.

Benefits and Ongoing Concerns

AI assistants offer several advantages. They can provide around-the-clock support, process large amounts of data quickly, and deliver insights tailored to individual financial situations. Experts at IBM note that advanced analytics can strengthen fraud detection by identifying suspicious transactions in real time.

However, concerns remain. Privacy, cybersecurity, algorithmic bias, and transparency continue to be important issues. Regulators and consumer advocates emphasize the need for responsible AI governance to ensure fair and secure financial services.

The Future of Financial Technology Services

As AI technology matures, digital banking assistants are expected to become more sophisticated and accessible. Future systems may combine financial education, wealth management, and risk monitoring within a single user experience. While challenges remain, ongoing innovation suggests AI-powered financial tools will play an increasingly important role in helping consumers make informed financial decisions.

How Technology Is Transforming Financial Planning for Veterinary Practices

veterinarian using a tablet with financial dashboards

Nearly 80% of small business owners say that digital tools have made managing money easier, faster, or more accurate, according to a study by the American Express Small Business Financial Trends Report. For veterinarians juggling long work hours, emergency calls, and client care, every minute saved on financial tasks is a minute gained for healing pets and building a thriving practice.

I still remember the first time I talked with a vet who said she almost missed her retirement contributions deadline because she was buried in cash flow spreadsheets, paper receipts, and tax estimates we all dread. Then she found ways to automate her planning, and boom, she had time to actually enjoy her rare Sunday afternoons off. Finance technology has that same sort of transformative potential. According to SG Wealth management, using tech to streamline financial planning helps veterinarians see the big picture without drowning in data.

Why Finance Technology Matters for Busy Veterinary Professionals

Veterinarians have one of the toughest schedules around. Early mornings. Late nights. The occasional panicked call about a scared puppy. It makes sense that complex spreadsheets and manual budgeting often get shoved to the bottom of the to-do list. Money matters, like investing for retirement, planning for tax seasons, or tracking clinic revenue, don’t wait for quieter days. They demand consistent attention.

Here’s where fintech — that’s finance technology — steps in like a good assistant you never had. Tools that automate tasks, reduce errors, and give you visual dashboards mean more clarity and less chaos. And clarity matters. When you can see trends in your spending, track investment performance, or project future clinic revenue moments after a shift ends, you make better decisions. That’s good for your wallet and your peace of mind.

Tech Tools That Streamline Investment Tracking and Risk Analysis

Imagine logging into an app and seeing all your financial accounts in one place. Retirement plans. Savings. Clinic earnings. Investment accounts. You get a dashboard that feels more like a clear roadmap than a jumbled inbox of receipts. That’s no longer a dream. Tools like automated portfolio rebalancers and AI-powered risk analyzers help you understand where your money is, how it’s working, and how to adjust when markets shift. Understanding the evolution of fintech helps veterinarians appreciate how these tools have bridged traditional finance with modern innovation, making complex strategies accessible at a glance.

Let’s talk about automated portfolio rebalancing. This feature adjusts your investments based on your target strategy without you lifting a finger. You’re busy. You’re tired. You deserve a system that keeps your portfolio aligned with your goals, even when your brain is on weekend detox mode. And that’s exactly what robo-advisors and modern platforms do, with safeguards and alerts so you stay informed.

Another compelling tool uses artificial intelligence to analyze cash flow patterns. It flags slow months and predicts future dips so you’re more prepared. In a clinic where expenses can spike because of new equipment, seasonal trends, or tax deadlines, this predictive insight can make the difference between stress and strategic planning.

Digital Platforms That Improve Communication with Your Financial Advisor in Canada

Communication with an advisor used to mean a stack of papers, a jam-packed inbox, and a lengthy call. Now, financial dashboards let you share data instantly. Screenshots. Secure access. Live updates. Advisors can review performance in real time with you. That means faster decisions and clearer strategies tailored to your goals, whether you’re saving for your first clinic expansion or finally planning that dream sabbatical.

In Canada, digital platforms have grown rapidly. Organizations like the Investment Industry Regulatory Organization of Canada and the Financial Consumer Agency of Canada ensure that fintech tools meet strong security and consumer protection standards. That’s huge because it means your sensitive financial data stays safe, while you benefit from innovation designed to reduce friction between you and your advisor.

One veterinarian I spoke with said her advisor used to send quarterly PDFs with updates that felt like cliff notes to a dense textbook. Now they meet monthly via a secure app, set goals together, and review performance quickly before she heads to the next appointment. It’s practical, efficient, and feels personal — even though it’s powered by technology.

Practical Steps to Adopt Fintech Solutions Without Sacrificing Personalization

Jumping into the world of fintech doesn’t have to feel like signing up for a rocket launch. Start with small steps. First, choose a secure financial dashboard that connects to your accounts. Make sure it has multi‑factor authentication and clear privacy policies. Next, explore automated tools for budgeting or investment tracking that match your comfort level. You don’t have to adopt every new tool at once.

Remember that technology supports your goals; it doesn’t replace your judgment or your advisor’s expertise. Always take time to understand how a tool works before handing it the keys to your financial house. Look for platforms that offer tutorial resources, customer support, and clear communication channels. Good technology should feel like a helpful team member, not a confusing puzzle.

Conclusion

Technology is changing financial planning for veterinary professionals in exciting ways. It cuts down busy work, brings big clarity to complicated concepts, and strengthens connections with financial advisors. For vets who want to grow clinic revenue, build wealth, and protect their future, adapting finance technology can feel like flipping a switch from chaos to calm. Whether you’re just starting out with digital dashboards or working with tools recommended by SG Wealth management’s team, technology can make financial planning less scary and more strategic. Embracing smart financial tools today means more time for what really matters, both in the clinic and in life.

How FinTech Apps and Digital Insurance Tools Are Making It Easier and Cheaper to Fight Traffic Tickets in 2025

traffic ticket alertOne speeding ticket can raise a driver’s insurance premium by hundreds of dollars over the next year, and many people do not realize the increase until the new bill arrives. This quiet jump in cost is one reason drivers are turning to modern financial tools for help.
Today, apps and dashboards built for personal finance and insurance management alert users the moment a ticket appears on their record. These tools then show the long-term financial impact with clear numbers. This shift has changed how people respond to violations, especially in states where legal help can make a big difference. Many Maryland drivers now check these tools first before taking action, which often leads them to a trusted Maryland traffic lawyer for advice.

Drivers have learned that a ticket is not just a legal issue. It is a financial event that affects monthly payments, credit behavior, and future insurance choices. Because of this, more people are treating violations like a financial emergency rather than an inconvenience. As FinTech grows, these tools are becoming faster and more accurate.

How Telematics Apps Spot Trouble Early

Telematics systems were once used only by major insurance companies. In 2025, they are now inside most modern finance apps. They track driving habits, location, and braking patterns to help create fair insurance rates. When a ticket hits a user’s motor record, these systems send instant alerts.

This real-time warning prevents drivers from being surprised by rate increases later. It also gives time to respond before the insurance company recalculates premiums. Some apps even show a projected premium change, which helps users decide whether to contest the ticket, pay the fine, or seek legal help.

Usage-Based Insurance Dashboards Simplify Decisions

Usage-based insurance has become popular because it rewards safer habits with lower monthly costs. The dashboards that support these plans now show the financial impact of every incident. A small violation can turn into a large yearly expense, so the dashboard might show a clear comparison between paying the fine or hiring help to reduce points.

For Maryland drivers, this has been especially important. Many users report that these dashboards encourage them to consult a Maryland traffic attorney when a violation threatens to spike their premiums. The clear numbers help them understand what is at stake.

AI-Powered Premium Predictors Show Long-Term Risk

AI is now central to modern insurance apps. Predictive models scan a user’s driving patterns, age, location, and ticket history. They then show how one violation might impact costs over one, two, or even three years. Seeing this projected loss in real numbers motivates drivers to act fast.

These tools also show how many points will remain on the record and when they drop off. This helps drivers plan ahead and avoid further mistakes that might trigger more increases. The transparency makes the legal and financial path forward easier to understand.

How Digital Payment Platforms Help Drivers Fight Back

Another major shift in 2025 is how people pay for legal help. Digital legal-payment platforms now connect directly to attorneys who handle traffic cases. These systems work much like modern digital banking service transactions, giving drivers fast and secure ways to move money when time matters.

Maryland drivers in particular have embraced these platforms. They can quickly hire a skilled Maryland traffic lawyer, pay online, and handle the entire case without missing work. When the cost of a violation threatens long-term insurance stability, that convenience matters. The platforms also use secure payment systems that many drivers already trust, which removes friction from the process.

Why Treating a Ticket Like a Financial Event Saves Money

The biggest mindset shift is simple. A ticket is a financial loss that repeats every month the insurance premium stays higher. When drivers understand that, they take action sooner. FinTech tools help them plan, compare costs, and make better choices that protect their budget.

Digital insurance dashboards show the immediate cost. AI models show the future cost. Telematics apps show the risk of further issues. Legal-payment platforms give fast access to help. Together, these tools turn a stressful moment into a manageable financial decision.

The Bottom Line

Drivers who treat violations as financial events can save thousands of dollars. FinTech apps make that easier by providing real-time alerts, clear projections, and simple paths to professional support. With tools that connect users directly to a reliable Maryland traffic lawyer, the process has become fast and affordable. In 2025, fighting a ticket is no longer about paperwork, it is about protecting long-term financial health.

Fintech Evolution: Bridging Traditional Finance and Innovation

fintech interface

Integration of Fintech in Corporate Finance

Fintech is no longer just about mobile apps and online payments. It’s transforming how corporations manage capital, assess risk, and evaluate investment opportunities. Tools powered by AI and machine learning are now commonly used to analyze company valuations, predict market trends, and optimize financial decisions.

Artificial Intelligence Is Leading the Charge

AI is one of the biggest drivers of fintech innovation in 2025. Companies use AI to automate financial analysis, detect fraud, and create personalized financial services. This shift is making services faster and more accurate. Consumers also benefit from faster loan approvals and smarter investment platforms.

Financial Inclusion Through Technology

Fintech continues to bring banking to unbanked populations worldwide. From rural areas in Africa to underserved Asian communities, mobile banking and crypto wallets offer people the ability to save, borrow, and invest without needing a traditional bank account. This technology is leveling the financial playing field globally.

Cybersecurity and Regulation Remain Critical

As fintech systems grow more complex, the risk of cyberattacks rises. Financial firms are investing in stronger security protocols and working with regulators to ensure that innovation does not come at the cost of safety. Countries are also updating laws to manage fintech growth better and protect users.

Conclusion

Fintech is no longer a niche—it’s becoming the backbone of modern finance. As it blends seamlessly with traditional systems, users and businesses will experience a more efficient, inclusive, and innovative financial future.

6 Reasons Why InfoNow Korea’s Micropayment Solutions Are a Game Changer for FinTech Startups

Young Korean professionals collaborating in tech office, showcasing mobile micropayment app interface screens.

In the evolution of the digital economy, mobile micropayments offer another avenue for conducting financial transactions. One of the leading players in this space is InfoNow Korea, whose innovative micropayment cashing solutions are transforming the FinTech industry.

If you want to know how these solutions can be beneficial from a competitive standpoint, here are six reasons InfoNow Korea’s micropayment system is revolutionizing FinTech for start-ups.

1. Easing Transaction Processes to Users

InfoNow Korea’s micropayment solution enables every consumer to make minute payments through their mobile phones. As a result, their integration interfaces do not require the users to possess credit cards or other payment apps, which greatly increases ease of use and encourages frequent transactions.

Whether it is confirming, ordering, or otherwise, the users can press one button and will be instantly guided through a plethora of steps without having to manually enter information.

2. Increasing Service Availability to Untapped Areas

Accessing underserved populations who do not have any form of banking services is one of the key advantages of InfoNow Korea’s system. This solution allows people from remote regions or places with limited credit facilities to perform micropayments via mobile phones, creating new markets for FinTech startups.

The continual increase of mobile penetration allows this regionalization of financial services to greatly enhance economic growth.

3. Innovative Protective Measures

E-commerce entails a greater risk concerning financial security. InfoNow Korea’s system is tailored to provide secure transactions using the latest encryption and authentication technologies.

With emerging risks that are associated with online payments, there is an increasing need for reliable and secure payment systems. Users and customers will be more willing to trust FinTech companies with their sensitive information, enabling the companies to reduce fraud concerns and increase customer loyalty.


ALSO READ: Fintech Innovations: AI and Blockchain Reshaping Finance


4. Economically Viable for FinTech Startups

The adaptive budget for startups leaning toward a higher risk can utilize the micropayment solutions provided by InfoNow Korea as a cost-effective method to process payments.

Savings in transaction costs resulting from the system’s low chargeable fees per transaction compared to credit card networks mean lower fees. As a result, such funds can be redirected to more important areas like marketing, product development, and customer acquisition, all of which drive business growth.

5. Real-Time Transactions and Instant Settlement

The micropayment platform developed by InfoNow Korea allows businesses and consumers to receive payments in real-time with an instantaneous confirmation of payment.

This feature ensures that payment delays do not occur while business funds are readily liquid for reinvestment, which is cash flow positive.

6. Encouraging Financial Inclusion

InfoNow Korea’s micropayment solution opens up new horizons for businesses and individuals by enabling simpler, low-cost payments. This solution provides a gateway to a diverse customer base for FinTech startups striving to bridge the financial gap.

Conclusion

The financial tech space is shifting paradigms with the use of InfoNow Korea’s micropayment solutions. These innovations assist fintech startups to increase their market reach while providing additional security and lower-cost payments and adjusting to the fast-paced digital economy.

Fintech Innovations: AI and Blockchain Reshaping Finance

ai and blockchain

The world of finance is undergoing a significant transformation driven by groundbreaking fintech innovations. Artificial intelligence (AI) and blockchain are among the most influential technologies that reshape how businesses and consumers approach financial transactions, security, and investment.

AI-Powered Banking

Artificial intelligence revolutionizes banking operations by enabling smarter, faster, and more secure services. Banks now leverage AI to enhance customer service through chatbots and virtual assistants, providing 24/7 support for queries and transactions. Additionally, AI is crucial in fraud detection, analyzing vast amounts of data to identify suspicious activities in real-time. By streamlining processes and minimizing risks, AI-powered solutions are making banking faster, safer, and more accessible to a global audience.

Blockchain for Secure Transactions

Blockchain technology is gaining traction as a powerful tool for ensuring transparency and security in financial transactions. By recording data on an immutable ledger, blockchain eliminates the need for intermediaries and reduces the risk of fraud. This technology is particularly appealing to businesses seeking efficient and trustworthy payment solutions. As more industries adopt blockchain, it becomes a cornerstone of secure and transparent financial practices.

Rise of Digital Wallets

The popularity of digital wallets is soaring as people increasingly prefer mobile payments over traditional cash transactions. Digital wallets like Apple Pay, Google Pay, and others allow users to make payments with just a tap of their smartphone or smartwatch. This convenience and growing acceptance by merchants have fueled a steady rise in digital transactions. As technology advances, digital wallets become more versatile, incorporating features like loyalty programs and international payments.

Fintech Startups Attract Investment

Fintech is a hotbed of innovation, attracting significant investment from venture capitalists and financial institutions. Startups are developing cutting-edge solutions in areas such as peer-to-peer lending, robo-advisors, and cryptocurrency exchanges. This influx of funding drives rapid expansion, fosters competition, and encourages the development of new products and services that challenge traditional financial models.

Conclusion

Fintech is undeniably transforming the global financial landscape. From AI-enhanced banking to blockchain-secured transactions and the rise of digital wallets, these innovations are shaping the future of finance. For businesses and consumers alike, staying informed and adapting to these changes is essential to thrive in this dynamic environment.

The Importance of Financial Technology

Financial technology is transforming how financial services are delivered, improving efficiency, accessibility, and convenience. It encompasses a wide range of innovations that use technology to automate, enhance, or disrupt traditional financial services. The growing importance of FinTech can be seen across personal finance, banking, payments, insurance, lending, and investment management.

https://www.gocashew.com